Filing crypto taxes can be a very daunting process, especially if you're involved in DeFi, trade on decentralized exchanges, or engage in any other type of complex crypto activity. However, it becomes much less of a challenge if you use the right tools and have a structured approach to tracking your crypto transactions.
We spoke with Berken Menges, who is the chief marketing officer of CoinTracking, a crypto tax reporting and portfolio tracking platform that has been operating since 2012 and is serving over 2.2 million investors.
We asked Berken about the current crypto tax reporting landscape, the challenges that have emerged with new types of blockchain-based platforms, as well as how the space will evolve in the future. He even shared some pro tips on how you can make your life a little bit easier when it comes to filing your crypto taxes.
Interview with CoinTracking CMO Berken Menges
What's the most common issue encountered by investors doing their crypto taxes for the first time?
The most common issue for first-time filers is not calculation, it is incomplete data. People expect the hard part to be working out what they owe. In practice the hard part is reconstructing what actually happened across several years and several platforms.
The pattern is almost always the same. Coins were moved between exchanges and wallets, so the original purchase price no longer travels with them and a transfer looks like a disposal. An exchange used in 2018 has since been acquired or now returnsonly a limited window of history through its API. A wallet was forgotten because it holds a small balance.
Each gap on its own is minor. Together they produce a report that does not reconcile. This is why CoinTracking puts as much work into data validation as into the tax calculation itself. Tools such as Account Check, ValiCheck and the Missing Transactions Report exist to find these gaps before a report is generated, rather than after a tax office asks about them.
The good news for anyone starting now is that this is a solved problem if you start from the data side.
Trading via perpetual futures on platforms like Hyperliquid is becoming an increasingly important part of the crypto market. Does on-chain trading pose any special challenges for investors when tax season comes around?
Perpetual futures and on-chain trading are genuinely one of the most interesting developments in this market, and Hyperliquid is the clearest example. The speed at which it has grown, and how much real volume has moved on-chain with it, is remarkable to watch. CoinTracking supports Hyperliquid imports, and we expect this part of the market to keep growing.
What makes derivatives different from spot trading is that the tax-relevant figure is the realised profit or loss on a closed position, not the individual orders. So the quality of a report depends on how well that data is made available. This is precisely why CoinTracking works directly with many of the largest exchanges worldwide, including as an official tax partner for some of them.
Close cooperation on data formats and API coverage is the most effective way to give users a clean result, and the industry has moved a long way here in the past two years. CoinTracking also has dedicated transaction types for margin and derivatives results, including margin gain and loss, derivatives and futures gain and loss, and settlement fees, so those positions land in the report correctly in the jurisdictions that treat them as capital gains.
On-chain trading adds a second dimension, because there is no account statement, only a wallet address and a very large number of interactions, including gas fees, wrapped assets and protocol-specific events that have to be interpreted before they can be classified. That is where a decade of building importers pays off, and where CoinTracking's optional Full-Service is used most by high-volume traders who would rather hand the reconstruction to a team.
How have crypto investors' tax-related needs changed since CoinTracking started operating in 2012?
CoinTracking has been in the market since 2012, and the needs have moved through three distinct phases. In the early years the users were a small group of early adopters, there were very few binding rules anywhere, and the demand was essentially for a better spreadsheet.
From roughly 2017 the retail wave arrived, and with it complexity that no spreadsheet could handle: staking, lending, DeFi, NFTs, hundreds of tokens and dozens of venues. The requirement shifted from record-keeping to correct classification of transaction types.
The current phase is different again, because the pressure now comes from outside the investor. Reporting frameworks in Europe and broker reporting in the United States mean that authorities increasingly receive data directly. The user's job is no longer to declare something nobody else can see, it is to make sure their own numbers are complete and consistent with what has been reported elsewhere.
That has also changed who the customer is. Alongside individual investors, CoinTracking works with tax advisors and firms through Corporate Accounts, and increasingly with platforms themselves, since exchanges and brokers now want to solve crypto tax reporting for their own customers rather than leave them to solve it alone.
Based on experiences with CoinTracking's userbase, do you perhaps have an underrated pro tip that will make life easier for crypto investors when it comes to crypto taxes?
Reconcile continuously instead of once a year. Concretely: connect a wallet or an exchange on the day you start using it, and run
a data check once a quarter rather than once in filing season.
The reason is unglamorous but it is the single biggest source of avoidable work. Historical data decays. Exchange APIs often return only a limited window. Platforms change their export formats or restrict old data. A wallet added three years after the fact has to be reconstructed from the chain, which is possible but far more effort than importing it once at the start.
An investor who spends fifteen minutes a quarter running something like CoinTracking's Missing Transactions Report will usually have a clean report in an afternoon. An investor who starts in filing season with five years of history spread over eight platforms is doing archaeology, under time pressure. The tip is boring, which is probably why it stays underrated.
What are users asking about most as broker reporting arrives in the US?
By some distance the most common question is why the Form 1099-DA shows a large proceeds figure and no cost basis, and whether the IRS now believes that figure is the user's profit.
The answer is that this is expected, not an error. Broker reporting is phased in. For 2025 transactions, brokers report gross proceeds only, which is why the noncovered box is checked on almost every 1099-DA issued this year. Basis reporting begins with transactions made on or after 1 January 2026, and even then it applies only to covered assets, meaning assets acquired and held in the same broker's account. Anything bought earlier, or transferred in from another platform or a self-custody wallet, remains noncovered.
So the gap between what a form shows and what a user actually owes will not close in 2027 either. Only the user's own complete history closes it. The second question is about the move to per-account tracking. Since the start of 2025, cost basis has to be tracked wallet by wallet and account by account rather than pooled across a whole portfolio, and many investors are still working out what that means for holdings they have carried for years.
The third is the mirror image of the first: users who receive no form at all, because they trade on non-US venues, in DeFi, or from self-custody, and want to know whether that changes their obligation. It does not. The practical advice we give is the same in all three cases. Do not prepare a return from the 1099-DA alone. Reconcile it against your own records, and be able to show how you arrived at your basis.
On the CoinTracking side, tax reports from 2025 onwards support assigning each transaction to the correct section of Form 8949, so that reported and unreported basis are separated the way the form requires instead of being merged into one total. For users who would rather not handle any of this themselves, CoinTracking's Full-Service covers the United States as well.
What can exchanges, brokers and banks do if they want to offer crypto tax reporting to their own customers?
This has become one of the most active parts of our business, and it is worth explaining, because most people only know CoinTracking as a consumer product.
CoinTracking offers its tax reporting as an embedded, white-label solution for exchanges, brokers and banks. In practice that means a platform's users can generate a tax report inside the platform they already use, powered by CoinTracking in the background, without creating a separate account or exporting files manually. It is the same engine that serves 2.2 million registered users, delivered through the platform's own interface.
The reason platforms want this is straightforward. Crypto tax is one of the largest support topics they face, and it is one they cannot fully answer on their own, because a platform only ever sees its own data while a typical user trades across several venues and holds assets in self-custody as well. Handing users a raw CSV is no longer a competitive answer, particularly as reporting obligations tighten.
An embedded reporting layer that can also ingest the user's other platforms turns an annual support burden into something the platform gets credit for, and it keeps the user inside the product at the one moment of the year when they would otherwise go looking elsewhere. For a company that has been building exactly this since 2012, it is not a new product. It is the same infrastructure with a different distribution model.
Are there any countries where CoinTracking has seen a substantial spike in signups recently?
We do not break out signup figures by country, but the underlying trend is more interesting than any single market anyway: awareness is simply growing. Crypto taxation is no longer a niche topic discussed in forums. It is covered in mainstream financial media, tax advisors have built practices around it, and investors who held quietly for years are now actively looking for a defensible way to report. That general increase in understanding is the strongest driver we see, and it is a healthy one, because it means people come to a tool early rather than in a panic.
Reporting frameworks contribute to that in a specific way. Their main effect, in our view, is not pressure but clarity. Once the rules and the timelines are visible, a certain type of investor stops postponing the topic and deals with it. Clarity moves more people than deadlines do.
What we can say concretely is where coverage has expanded. France and Czech Republic went live on 20 August 2026, which brings CoinTracking to 22 country-specific tax reports. Both were a direct response to demand from those markets.
What does CoinTracking do better than other crypto tax software tools?
The honest answer starts with how the company is built rather than with a feature list. CoinTracking has been bootstrapped since 2012 and has never had an outside roadmap imposed on it, which means the product has grown almost entirely out of user feedback.
When users asked for a transaction type, a tax method, an exchange, a country report, it got built. That is a very ordinary way to work, but over thirteen years it compounds, and it is quite close to the original ethos of this industry: build for the people actually using the thing.
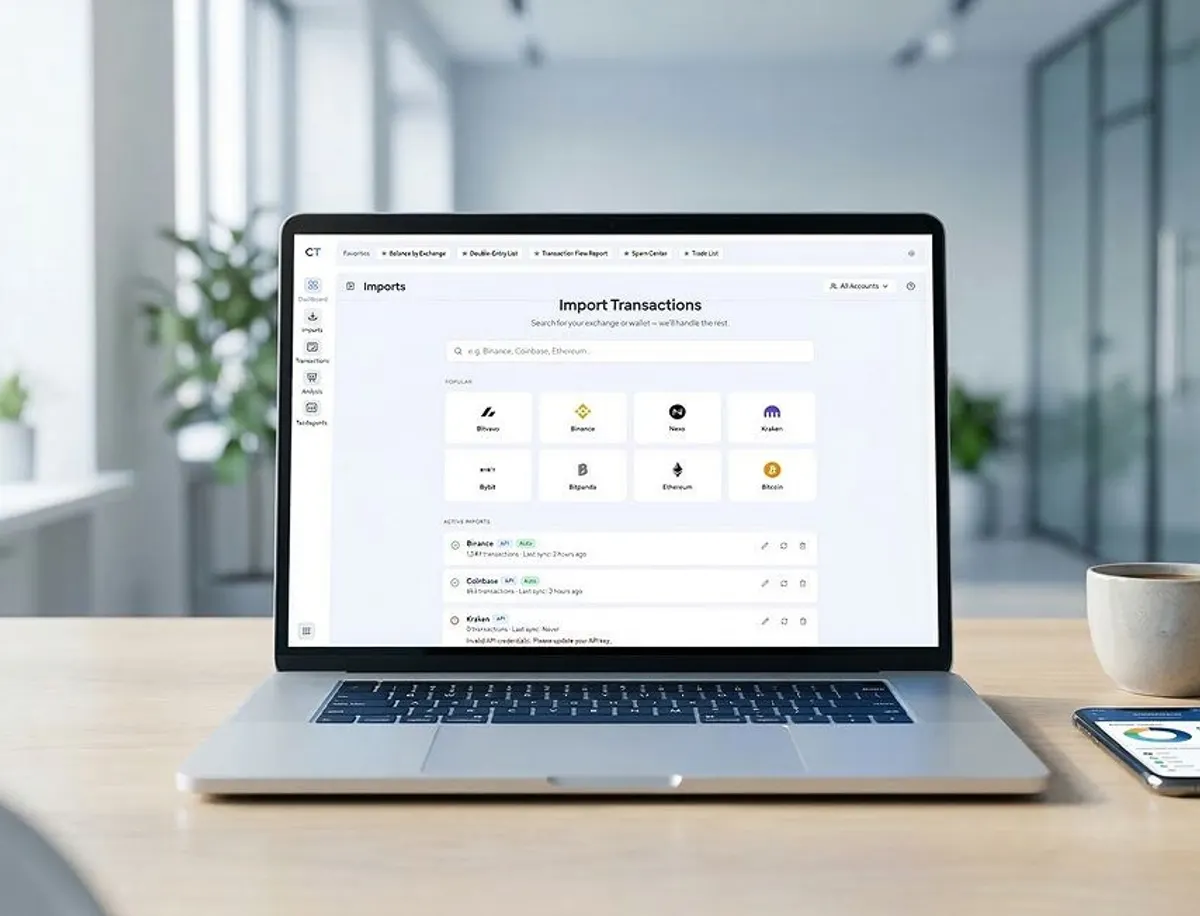
The visible result is depth. CoinTracking supports 400+ integrations across exchanges, wallets and blockchains, produces country-specific tax reports for 22 countries, and covers every other jurisdiction through a configurable General Tax Report supporting FIFO, LIFO, HIFO, ACB, AVCO and HMRC, including per-year method selection. None of that came from a strategy document. It came from users with a specific problem that nobody else would solve for them.
The same is true of the part that pure software tools do not offer at all. Users kept asking whether someone could simply do it for them, so CoinTracking built an optional, separately priced Full-Service, available in more than 25 countries, in which an expert team takes over the imports, the validation and the creation of the report. In countries where CoinTracking has a certified tax partner, that partner can also prepare and file the return.
The last point is continuity. For a tool whose value depends on holding a decade of someone's financial history, staying in business is a feature. CoinTracking has run since 2012, serves more than 2.2 million registered users, is ISO/IEC 27001:2017 certified, hosts all data on servers inside the European Union, and allows registration without an email address.
Are there any markets that CoinTracking is looking to expand to?
We add country-specific reports where two conditions are met: there is real user demand, and the local rules are settled enough that a report can be built without guessing. France and Czech Republic were the two most recent additions, in August 2026.
We do not pre-announce the next ones, mainly because a report that ships before the rules are stable helps nobody.
The expansion that matters most to us right now, though, is not geographic. It is the shift from serving investors directly to also serving the platforms they use, which is the embedded reporting model described above.
Looking five years ahead, what do you think crypto tax software will need to do that it doesn't do today?
Three things, in order of how confident I am about them. The first is that cost basis will have to travel with the asset. Today, the moment a coin moves between platforms, its acquisition history is lost and the user has to restore it manually. That is the single largest source of error in the entire category, and it is a solvable interoperability problem rather than a tax problem. Whoever solves it well removes most of the pain in one step.
The second is AI, and specifically in the place where it is actually useful. The hard, slow part of crypto tax is not arithmetic, it is interpretation: deciding what an unlabelled on-chain interaction was, whether an incoming transfer is income or a transfer between your own wallets, which protocol event corresponds to which taxable category. That is pattern recognition on messy data, which is what modern models are good at.
In five years I expect classification to be largely automated, with the model flagging what it is unsure about rather than guessing, and I expect users to interrogate their own tax position in plain language instead of building filters. What will not change is that a report has to be defensible, so human review stays part of the process. The interesting question is not whether AI does the work, it is how transparently it can show its reasoning to a tax office.
The third is reconciliation against what authorities already hold. As reporting frameworks mature, tax administrations will receive a growing share of this data directly. Software will need to compare a user's own position against what has been reported about them and explain any difference in terms a human can act on.
We'd like to thank Berken Menges for taking the time to thoroughly answer our questions.